States Can’t Count On More Federal Bailout Money, Bowles Tells Governors

Posted By on July 11, 2010

By Michael McDonald       Jul 11, 2010

States can’t count on the federal government for more budget bailouts, the heads of President Barack Obama’s debt commission told governors today.

States that are expecting Congress to authorize more bailout money are “going to be left with a very large hole to fill,” said Erskine Bowles, co-chairman of the National Commission on Fiscal Responsibility and Reform. States including New York and California have urged Congress to extend stimulus spending authorized to combat the recession, including extra Medicaid funding and money to pay public school teachers.

“I don’t think we can count on the federal government again,” Bowles, White House chief of staff under former President Bill Clinton, said at the National Governors Association meeting in Boston. “They just do not have the financial resources.”

While the economy has been expanding, states have yet to recover from the longest recession since the Great Depression. The economic rout cut into tax collections and led them to raise taxes and slash spending on schools, social services and other expenses. States have projected total budget deficits of $127 billion through 2012, according to a report last month by the governors association and the National Association of State Budget Officers.

http://www.bloomberg.com/news/2010-07-11/states-can-t-count-on-more-federal-bailout-money-bowles-tells-governors.html

Debt Is Still The Major Problem And Deflation Is The Painful Solution

Posted By on July 10, 2010

Comstock Partners, Inc.

Posted July 10, 2010
Velocity Is the Key

We understand that we have discussed the debt problem in this country for what seems to be forever, but we can’t stop talking about it now that the debt is clearly the catalyst for the latest stock market downturn.  Debt is discussed by the pundits on financial TV also, but in almost every case the discussion revolves around government deficits relative to GDP or government debt relative to GDP.  They are constantly comparing the U.S. government debt to every other country in the world (especially Portugal, Italy, Ireland, Greece, and Spain-PIIGS).  We believe that the government debt should be taking a back seat to the private debt which is much larger and must eventually be deleveraged.

The private debt is about 6 times larger than our government’s public debt; about 4 times larger than our government’s gross debt (including the government debt used to fund our Social Security shortfall);  and about 2.5 times the gross government debt plus the total state and local debt.  Household debt alone is equal to 96% of GDP; private domestic nonfinancial debt is 183% of GDP; total credit market debt is 357% of GDP (see first chart Selected Debt Measures as a % of GDP).  Please note that the only form of debt that isn’t rolling over is the government debt.

We have been predicting for over 3 years that the government debt (including public, gross, and state and local governments) will increase substantially, while the private debt (all forms) will roll over and decline substantially.   In round numbers total credit market debt is $55 trillion and government debt is $15 trillion, leaving private debt at approximately $40 trillion.  We have drawn debt cones (see 2nd chart-debt cones) to illustrate the concept.  We believe the government debt will rise towards the $30 trillion level while the private debt will drop towards the $20 trillion level.  This coincides with the Cycle of Deflation (next chart) which we authored years ago.

This debt scenario is bad enough, but when you take into consideration the unfunded liabilities that we are saddled with in the future– with social security, medicare and medicaid, you can add another $80 trillion onto the $50+ trillion of total credit market debt today.  By the time the baby boomers retire, the 40 million residents presently over the age 65 will rise to 72 million.  We are talking about a large number of relatively unhealthy people who will live well into their 80s.    These are facts that are being disseminated to the masses now and if that doesn’t scare the younger population that will have to pick up this burden I don’t know what will.  

Most bears on the stock market are fearful that the Administration and Fed are printing far too much money and this will result in potential runaway inflation. We, on the other hand, do not think the results of the Fed’s balance sheet increasing through quantitative easing (QE) will result in inflation in the next few years, although it could very well be a serious problem further down the road.  We believe the private sector debt will continue to decline (deleverage) regardless of what the Fed and Administration do to attempt to jolt the economy. 

The reason that the attempt at money printing to juice the economy will not work, in our opinion, is that the whole private sector is frozen due to the fear of losing more money.  Corporations are continuing to build up cash positions and individuals are afraid of taking risk in this environment.  The latest economic releases verify our opinion that the private sector is losing confidence.  Corporations are afraid to take on more employees—we gained only 33,000 jobs in the private sector in May and just last week reported a disappointing gain of 83,000 jobs in the private sector. It would take average monthly increases of over 130,000 jobs just to keep up with the average gain in the labor force. Last week the Conference Board reported that the Consumer Confidence index for June declined to 52.9 from 62.7 in May.  New single family home sales collapsed 32.7% from April to a record low rate of 300,000 (see the next two attached charts).  There are estimates of about 10 months of shadow inventory of foreclosed homes currently off the market and not included in the national inventory.  The national inventory of homes available rose to 8.5 months supply in May.  Today it was announced that demand for mortgages to buy homes dropped 2%.  It was the 8th weekly drop in the 9 weeks since the credit for home buyers expired on April 30th.  We just recently wrote a comment dealing with the potential for a second dip in housing prices on June 10th titled “The Dire Outlook for Housing”.  

The Fed believed that Quantitative Easing (QE) would stimulate the economy much more than it did.  QE includes all of the measures the central bank takes to increase the monetary base, hoping that this translates into increased money supply.  However, in the current credit crisis QE is not working as well as the Fed and Administration expected.  While it has succeeded in jump-starting the monetary base it has failed to increase the money supply or velocity (the ratio of economic transactions to the money supply).  Thus, while the banks now have the ability to make new loans, not enough qualified borrowers are interested in borrowing money, and banks are not willing to  loan money to anyone that is not a prime borrower.    What we need to stimulate the economy is “velocity” which measures the rate at which money in circulation is used for purchasing goods and services.  The velocity of money is computed by dividing the nation’s output of goods and services by the total money supply (circulating currency plus checking account deposits).  Velocity of money is also influenced by interest rates.  When rates are low, people hold more money in cash, when rates are rising, they put more money in interest paying investments. 

When velocity is low the nation essentially winds up in a “liquidity trap” which is a situation where monetary policy is unable to stimulate the economy either through lowering interest rates or increasing the money supply.  This was the condition that Japan found itself enveloped in from 1989 to present.  We expect the same problem in this country and hope (really hope) to be wrong.  If we are lucky we will be able to go through the slowdown we expect (or double dip) and repair the household balance sheets enough to grow out of this mess in less time than it is taking Japan.   

The materials in this website are not an offer to sell or solicitation of an offer to buy any security , nor shall any such security be offered or sold to any person, in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under the securities laws of such jurisdiction.  Investors should consider the investment objectives, risks, sales charges and expense of the fund carefully before investing. The prospectus contains more complete information about this and other matters. The prospectus should be read carefully before investing.

http://www.comstockfunds.com/screenprint.aspx?newsletterid=1534

British Petroleum Takes A Big Chance

Posted By on July 10, 2010

BP removes old cap; oil runs free as new cap is prepared…….Let’s hope this works.   With British Petroleums record, we wouldn’t want to be in their shoes.

Engineers began work Saturday on installing a new, tighter-fitting containment cap for the Gulf spill. They removed the old cap, which temporarily means oil is gushing out unabated. The new seal could be on in four to seven days.

Robert Reich………The Vanishing American Consumer And The Coming Trade War

Posted By on July 9, 2010

So, you say who is Robert Reich………….

Robert Reich was the nation’s 22’nd Secretary of Labor and a professor at the University of California at Berkeley.

He has served as labor secretary in the Clinton administration, as an assistant to the solicitor general in the Ford administration and as head of the Federal Trade Commission’s policy planning staff during the Carter administration.

He has written eleven books, including The Work of Nations, which has been translated into 22 languages; the best-sellers The Future of Success and Locked in the Cabinet, and his most recent book, Supercapitalism. His articles have appeared in the New Yorker, Atlantic Monthly, New York Times, Washington Post, and Wall Street Journal. Mr. Reich is co-founding editor of The American Prospect magazine. His weekly commentaries on public radio’s “Marketplace” are heard by nearly five million people.

Mr. Reich has been a member of the faculties of Harvard’s John F. Kennedy School of Government and of Brandeis University. He received his B.A. from Dartmouth College, his M.A. from Oxford University, where he was a Rhodes Scholar, and his J.D. from Yale Law School.

By Robert Reich                    Jul 9, 2010  

President Obama has vowed to double U.S. exports within the next five years. That’s because exports are critical for rebooting the American economy. It’s clear American consumers can’t get the economy going on their own. They can’t restart the jobs machine. They’ve run out of money and credit.

It’s not just that one out of four Americans is unemployed or underemployed (working part-time, overqualified, or at a lower wage than before). More significantly, the Great Recession burst the housing bubble that had let American consumers turn their homes into ATMs. Now the cash machines are closed.

So the Administration figures foreign consumers will have to fill the gap.

Problem is, most other economies also relied on American consumers. Remember the trade gap? Americans used to be the world’s biggest and most reliable customers – sucking in high-tech gadgets assembled in China, car parts from Japan, shirts and shoes from Southeast Asia, and precision instruments from Germany.

With American consumers pulling back, these other economies have also been slowing down. Their unemployment is rising.

Last week I attended a conference with global business executives. When I asked them where they expected to find new customers to replace Americans who are pulling back, they all said China and India and quoted me the same number: 800 million new middle-class consumers from these and other fast-developing countries over the next decade.

Yes, but. As of now China and India are still relying on net exports to fuel their growth. Even if you think their middle classes will eventually become so big and rich they can buy everything these nations will be able to produce, that doesn’t mean they’ll also buy what the rest of the world produces.

Yes, global companies will do wonderfully well. General Motors is well on the way to selling more cars in China than it does in the U.S. But American workers won’t get the jobs, and nor will workers in Europe, Japan, or the rest of the world. GM makes the cars it sells to Chinese consumers in China.

Meanwhile, the productive capacities of China and India will continue to grow: More workers, more factories, more high-tech equipment, more offices. The buying power of their middle classes will have to expand rapidly just to catch up with what these nations will be able to produce.

This means Obama and others won’t easily find the export markets they need to create enough jobs to make up for the vanishing American consumer.

When the world’s productive capacities exceed the buying power of the world’s consumers, every government wants to increase exports and discourage imports. That spells trade war.

Last week the representatives of the world’s 20 biggest economies vowed to slash their budget deficits by half by 2013. The result will be even less domestic demand and even more pressure to export in order to avoid higher joblessness.

We’re unlikely to see a repeat of the disastrous Smoot-Hawley tariffs that worsened and lengthened the Great Depression. But you can forget trade-opening agreements. In Toronto last week, the G-20 leaders dropped their 2009 pledge to finish the Doha round this year. In the U.S., agreements with South Korea, Panama, and Columbia are languishing.

And watch out for under-the-radar protectionist moves. Since the start of 2008, when the Great Recession began, countries around the world have already imposed at least 443 measures to block imports, according to the Center for Economic Policy Research.

This is just the start.

http://wallstreetpit.com/34553-the-vanishing-american-consumer-and-the-coming-trade-war

The Three Waves Of New Taxes

Posted By on July 9, 2010

In just six months, the largest tax hikes in the history of America will take effect.  They will hit families and small businesses in three great waves on January 1, 2011:

First Wave: Expiration of 2001 and 2003 Tax Relief

In 2001 and 2003, the GOP Congress enacted several tax cuts for investors, small business owners, and families.  These will all expire on January 1, 2011:

Personal income tax rates will rise.  The top income tax rate will rise from 35 to 39.6 percent (this is also the rate at which two-thirds of small business profits are taxed).  The lowest rate will rise from 10 to 15 percent.  All the rates in between will also rise.  Itemized deductions and personal exemptions will again phase out, which has the same mathematical effect as higher marginal tax rates.  The full list of marginal rate hikes is below:

– The 10% bracket rises to an expanded 15%
– The 25% bracket rises to 28%
– The 28% bracket rises to 31%
– The 33% bracket rises to 36%
– The 35% bracket rises to 39.6%

Higher taxes on marriage and family.  The “marriage penalty” (narrower tax brackets for married couples) will return from the first dollar of income.  The child tax credit will be cut in half from $1000 to $500 per child.  The standard deduction will no longer be doubled for married couples relative to the single level.  The dependent care and adoption tax credits will be cut.

The return of the Death Tax.  This year, there is no death tax.  For those dying on or after January 1 2011, there is a 55 percent top death tax rate on estates over $1 million.  A person leaving behind two homes and a retirement account could easily pass along a death tax bill to their loved ones.

Higher tax rates on savers and investors.  The capital gains tax will rise from 15 percent this year to 20 percent in 2011.  The dividends tax will rise from 15 percent this year to 39.6 percent in 2011.  These rates will rise another 3.8 percent in 2013.

Second Wave: Obamacare

There are over twenty new or higher taxes in Obamacare.  Several will first go into effect on January 1, 2011.  They include:

The “Medicine Cabinet Tax”  Thanks to Obamacare, Americans will no longer be able to use health savings account (HSA), flexible spending account (FSA), or health reimbursement (HRA) pre-tax dollars to purchase non-prescription, over-the-counter medicines (except insulin).

The “Special Needs Kids Tax”  This provision of Obamacare imposes a cap on flexible spending accounts (FSAs) of $2500 (Currently, there is no federal government limit).  There is one group of FSA owners for whom this new cap will be particularly cruel and onerous: parents of special needs children.  There are thousands of families with special needs children in the United States, and many of them use FSAs to pay for special needs education.  Tuition rates at one leading school that teaches special needs children in Washington, D.C. (National Child Research Center) can easily exceed $14,000 per year.  Under tax rules, FSA dollars can be used to pay for this type of special needs education.  

The HSA Withdrawal Tax Hike.  This provision of Obamacare increases the additional tax on non-medical early withdrawals from an HSA from 10 to 20 percent, disadvantaging them relative to IRAs and other tax-advantaged accounts, which remain at 10 percent.

Third Wave: The Alternative Minimum Tax and Employer Tax Hikes

When Americans prepare to file their tax returns in January of 2011, they’ll be in for a nasty surprise—the AMT won’t be held harmless, and many tax relief provisions will have expired.  The major items include:

The AMT will ensnare over 28 million families, up from 4 million last year.  According to the left-leaning Tax Policy Center, Congress’ failure to index the AMT will lead to an explosion of AMT taxpaying families—rising from 4 million last year to 28.5 million.  These families will have to calculate their tax burdens twice, and pay taxes at the higher level.  The AMT was created in 1969 to ensnare a handful of taxpayers.

Small business expensing will be slashed and 50% expensing will disappear.  Small businesses can normally expense (rather than slowly-deduct, or “depreciate”) equipment purchases up to $250,000.  This will be cut all the way down to $25,000.  Larger businesses can expense half of their purchases of equipment.  In January of 2011, all of it will have to be “depreciated.”

Taxes will be raised on all types of businesses.  There are literally scores of tax hikes on business that will take place.  The biggest is the loss of the “research and experimentation tax credit,” but there are many, many others.  Combining high marginal tax rates with the loss of this tax relief will cost jobs.

Tax Benefits for Education and Teaching Reduced.  The deduction for tuition and fees will not be available.  Tax credits for education will be limited.  Teachers will no longer be able to deduct classroom expenses.  Coverdell Education Savings Accounts will be cut.  Employer-provided educational assistance is curtailed.  The student loan interest deduction will be disallowed for hundreds of thousands of families.

Charitable Contributions from IRAs no longer allowed.  Under current law, a retired person with an IRA can contribute up to $100,000 per year directly to a charity from their IRA.  This contribution also counts toward an annual “required minimum distribution.”  This ability will no longer be there.

Read more: http://www.atr.org/sixmonths.html?content=5171#ixzz0tCsweUWa

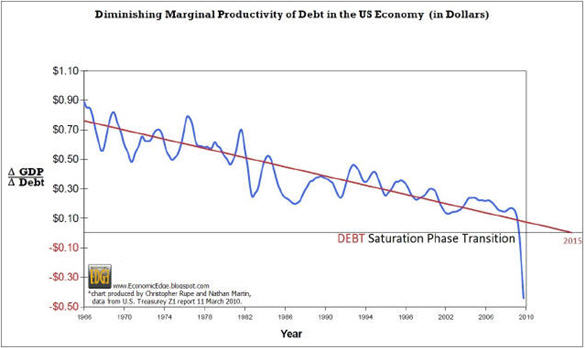
The Diminishing Marginal Productivity Of Debt In The U.S. Economy

Posted By on July 8, 2010

 Diminishing Margin Of Debt

The problem is actually pretty simple. We have more debt than productive growth can support. Debt has been losing its marginal productivity for years now and it no longer increases GDP. Rather, we abruptly reached debt saturation and now growth in debt reduces GDP. We have such levels of mal-investment and excess balance sheet gearing that increased debt now directly subtracts from productive money. Stimulus spending no longer will add sustained job growth.

Gordon T Long

Federal Budget Deficit Hits $1 Trillion For 1st 9 Months Of FY’10

Posted By on July 8, 2010

WASHINGTON -(Dow Jones)- The federal budget deficit for the first nine months of the 2010 fiscal year was just over $1 trillion, the Congressional Budget Office reported Wednesday.

The shortfall, reflecting $2.6 trillion in outlays for the first three quarters and $1.6 trillion in receipts, narrowed slightly compared with the same point in fiscal 2009.

Receipts were 0.5% higher for the period compared to the first three quarters of 2009, CBO said in its monthly budget review.

The rise in revenues was a result of increased corporate tax collections, due to improving economic conditions, and a shift by the Federal Reserve to higher- yielding investments.

But individual income and payroll tax receipts were down 4% over the nine- month period, suggesting that wages and salaries have not improved to the extent that corporate profits have.

More…

Consumer Credit In U.S. Fell Unexpectedly By $9.1 Billion In May, Fed Says

Posted By on July 8, 2010

By Vincent Del Giudice        Jul 8, 2010  

Consumer borrowing in the U.S. dropped in May more than forecast, a sign Americans are less willing to take on debt without an improvement in the labor market.

The $9.1 billion decrease followed a revised $14.9 billion slump in April that was initially estimated as a $1 billion increase, the Federal Reserve reported today in Washington. Economists projected a $2.3 billion drop in the May measure of credit card debt and non-revolving loans, according to a Bloomberg News survey of 34 economists.

Borrowing that’s increased twice since the end of 2008 shows consumer spending, which accounts for about 70 percent of the economy, will be restrained as Americans pay down debt. Banks also continue to restrict lending following the collapse of the housing market, Fed officials said after their policy meeting last month.

Economists’ projections in the Bloomberg survey ranged from a decrease of $5.2 billion to an increase of $2 billion in May. The central bank’s report doesn’t cover borrowing secured by real estate, such as home equity loans.

More at:    http://www.bloomberg.com/news/2010-07-08/consumer-credit-in-u-s-declined-by-more-than-forecast-9-1-billion-in-may.html

New Find….Antibody That Kills 91% of HIV Strains, But Must Be Perfected First

Posted By on July 8, 2010

July 08,2010

In a significant step toward an AIDS vaccine, U.S. government scientists have discovered three powerful antibodies, the strongest of which neutralizes 91% of HIV strains, more than any AIDS antibody yet discovered.  Looking closely at the strongest antibody, they have detailed exactly what part of the virus it targets and how it attacks that site.

The antibodies were discovered in the cells of a 60-year-old African-American gay man, known in the scientific literature as Donor 45, whose body made the antibodies naturally. Researchers screened 25 million of his cells to find 12 that produced the antibodies. Now the trick will be for scientists to develop a vaccine or other methods to make anyone’s body produce them.

That effort “will require work,” said Gary Nabel, director of the Vaccine Research Center at the National Institute of Allergy and Infectious Diseases, who was a leader of the research. “We’re going to be at this for a while” before any benefit is seen in the clinic, he said.

Full article at: www.wsj.com

Baltic Dry Shipping Index Drops Another 4%, Longest Decline On Record Enters 31st Day

Posted By on July 8, 2010

Records are made to be broke….

By Tyler Durden         07/08/2010

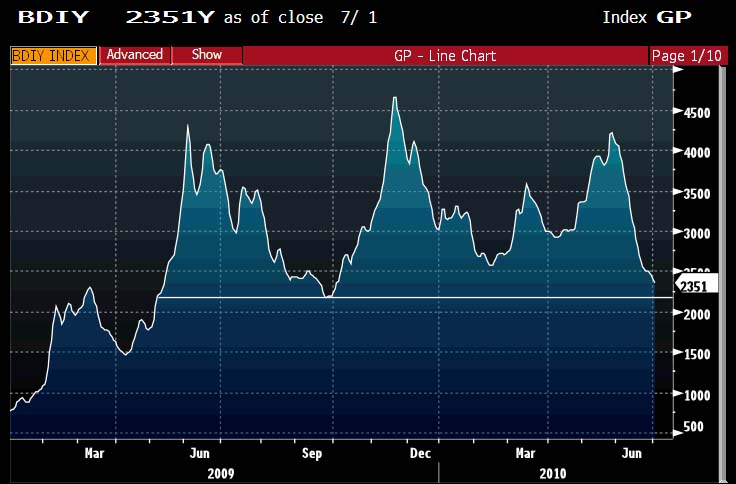
The Baltic Dry Shipping Index, which contrary to what some may claim, actually is one of the best leading indicators on global trade and thus the health of the economy, continues to plunge, and is now below 2000, hitting fresh 14 month lows, at 1940. It is now at the levels last seen during the March 2009 “generational” low, and just after the Lehman bankruptcy.
                www.zerohedge.com

IMF Warns Over US Housing, Unemployment, Consumer And Strong Dollar Risks

Posted By on July 8, 2010

Nice of the IMF to warn us……….

By Tyler Durden    07/08/2010

The IMF has issued a less than stellar outlook of the US economy after consultations with US government authorities, in which it cautions that even as the outlook has generally improved, major downside risks remain: “On the downside, the backlog of foreclosures and high levels of negative equity, combined with elevated unemployment, pose risks of a double dip in housing; the continued deterioration in commercial real estate poses risks for smaller banks; and financing conditions remain tight, especially for smaller firms reliant on bank finance. Most recently, and tipping the balance of risks to the downside, sovereign strains in Europe have become an increasing concern, potentially impacting the United States through financial market and, in a tail risk scenario, trade links.” Also notable is the fund’s warning on the state of the US consumer and the perceived overvaluation of the dollar: “It follows, as also emphasized in last year’s Article IV, that the United States can no longer play the role of global consumer of last resort, underscoring the importance of measures to boost growth and demand in current account surplus countries. With the U.S. dollar now moderately overvalued from a medium term perspective, this will need to be accompanied by greater exchange rate flexibility/appreciation elsewhere.”

www.zerohedge.com

Mortgage Rates Fall To All Time New Lows

Posted By on July 8, 2010

Now all you have to do is qualify!

Today, Freddie Mac announced that the 30 Year FRM declined to a new all time record low, dropping by 1 bp to 4.57% from the week before. Yet even as mortgage rates hit fresh weekly records courtesy of the Fed’s undisputed control of the mortgage market, the only thing increasingly more certain is that even at 0.00% there is precious little marginal demand in the primary market for housing. Here are the latest  observations from Rosie on precisely this phenomenon, and much more.

Just to show what little effect it is having, refinancing activity in the U.S. is still some 40% lower than it was the last time we had a major rally in the bond market in late 2008 and early 2009. In fact, coming out of the 1990-91 recession and the 2001 recession, the YoY trend in mortgage refinancing was over 1,000%(!), not 157%, just to put this in some perspective. The reason for the anemic growth this time around is because at the historic lows in yields, which we saw a year and half ago, just about everyone who could at the time managed to refinance, so today’s rally does them little good. Plus, with one in four mortgage debtors “upside down”, they don’t have the ability to refinance. But every penny counts, and the bond market is doing the best it can to get things going.

If there is a disturbing development, it is the lack of response on the part of potential homebuyers to the downdraft in mortgage rates. Demand remains anemic, and perhaps this reflects an aversion to taking on debt, and an aversion to buying a depreciating asset. Or perhaps it reflects the allure of landlords dropping their apartment rents and thereby upsetting the rent-buy decision balance. Maybe the White House should embark on a strategy of forcing landlords to hike their rents in a quest to revive the homeownership rate — it’s not as if this group doesn’t believe in government intrusion into the economy.

So, for the third week in a row, and despite a 13bp bond-induced decline in mortgage rates, applications for new purchases fell (by 2%) and are down 35% from year-ago levels; and those year-ago levels were already down 12%. So, after plunging 18% in May and then by 15% in June, mortgage apps for new home purchases are already down 3.4% so far in July. Clearly, as far as the Treasury market is concerned, more needs to be done — and since Mr. Bernanke is done cutting rates, it will be up to Mr. Bond to carry the ball, and likely a little further.

We are seeing first-hand how the economy operates when the policy stimulus are taken away — for example, a 0.8% annualized growth rate in real final sales as we saw in the first quarter. Don’t think for a second that we are going to see an upturn without some major exogenous shock. If it’s not the Fed or more fiscal spending, then it will have to be China (wasn’t it the world’s saviour in late 2008? Can it turn a blind eye to its credit and property bubble at the same time?), the ECB (will more ease peeve off the Germans?) or perhaps a payroll tax holiday in the U.S.A. (likely a better idea than turning the economy into a welfare state) or anything that will lift this cloud of uncertainty over the small business sector in particular (but is it too late to make any changes to the health care overhaul?).

http://www.zerohedge.com/article/freddie-30-year-fixed-rate-mortgage-rates-fresh-all-time-lows-are-little-help-housing-rosies

IMPACT: Gulf Awash In 27, 000 Abandoned Oil And Gas Wells

Posted By on July 7, 2010

Wednesday   Jul. 07, 2010

By JEFF DONN and MITCH WEISS – Associated Press Writers

Leading environmental groups and a U.S. senator on Wednesday called on the government to pay closer attention to more than 27,000 abandoned oil and gas wells in the Gulf of Mexico and take action to keep them from leaking even more crude into water already tainted by the massive BP spill.

The calls for action follow an Associated Press investigation that found federal regulators do not typically inspect plugging of these offshore wells or monitor for leaks afterward. Yet tens of thousands of oil and gas wells are improperly plugged on land, and abandoned wells have sometimes leaked offshore too, state and federal regulators acknowledge.

Melanie Duchin, a spokeswoman with Greenpeace, said she was “shell-shocked” by the AP report and upset that government wasn’t “doing a thing to make sure they weren’t leaking.”

Of 50,000 wells drilled over the past six decades in the Gulf, 23,500 have been permanently abandoned. Another 3,500 are classified by federal regulators as “temporarily abandoned,” but some have been left that way since the 1950s, without the full safeguards of permanent abandonment.

Petroleum engineers say that even in properly sealed wells, the cement plugs can fail over the decades and the metal casing that lines the wells can rust. Even depleted production wells can repressurize over time and spill oil if their sealings fail.

Regulators at the Minerals Management Service – recently renamed the Bureau of Ocean Energy Management, Regulation and Enforcement – have routinely been accepting industry reports on well closures without inspecting the work. And no one – in industry or government – has been conducting checks on wells that have been abandoned for years.

In its investigation, the AP found a series of warnings. For instance, the General Accountability Office, which investigates for Congress, warned in 1994 that leaks from offshore abandoned wells could cause an “environmental disaster.” The report stated: “MMS does not have an overall inspection strategy for targeting its limited resources to ensuring that wells are properly plugged and abandoned.”  The GAO report suggested MMS set up an inspection program, but the agency never did.

According to a 2001 study commissioned by MMS, agency officials were “concerned that some abandoned oil wells in the Gulf may be leaking crude oil.” But nothing came of that warning.

The oil that has been gushing from a BP PLC well since an exploratory oil rig exploded April 20 is an uncomfortable reminder of the potential for leaking at abandoned wells. The well was being prepared for temporary abandonment when it blew out, setting off one of the worst environmental disasters in U.S. history.

Wells are abandoned temporarily for a variety of reasons. In the case of the BP spill, the well was being capped until a later production phase. Oil companies also may temporarily abandon wells as they re-evaluate their potential or develop a plan to overcome a drilling problem or damage from a storm. Some owners temporarily abandon wells to await a rise in oil prices.

Read more:http://www.kentucky.com/2010/07/07/1338954/ap-impact-gulf-awash-in-27000.html#ixzz0t3zgopCK

New…..NSA Cyber Shield For Infrastructure

Posted By on July 7, 2010

From   The Wall Street Journal

From what we have heard and read, something similar to this has been in the works for some time.

The U.S. plans a program, called “Perfect Citizen,” to detect cyber assaults on companies and government agencies running critical infrastructure which include the electricity grid and nuclear power plants.

The Coolest Place To Be

Posted By on July 7, 2010

Record low temperatures in San Diego

By Gary Robbins , UNION-TRIBUNE STAFF WRITER

Updated July 7, 2010

While much of the nation swelters, in San Diego people have to bundle up at the beach.

This is July?   It didn’t feel that way as high temperatures were at record lows in San Diego County today, says the National Weather Service. It was quite a contrast from the East Coast, where such big cities as New York, Philadelphia and Baltimore experienced record highs.

A trough of low pressure and a thick marine layer kept most of the western half of the county cloaked in clouds for much of the day.

The temperature only reached 62 degrees in Oceanside Harbor. The record “low high” for this date is 65. That record was set in 2002. The harbor averages a high of 74 degrees this time of year.

Escondido posted a high of 69, which was nine degrees below the lrecord ow-high, set in 1987. The city averages 87 degrees in early June.

At Lindbergh Field in San Diego, the temperature reached 65, tying the low-high for this date, set in 1912. The normal temperature for this time of year in 75. And in El Cajon, the temperature hit 78, trying the record low-high, set in 2002. El Cajon’s average high is 86.

Wednesday could be another day for the record books. The weather service says the marine layer will hang around coastal areas more of the day.

It’ll be hot back east, too. The temperature hit 105 today in Baltimore, 102 in New York and Philadelphia and 100 in Boston. The first three cities set records for this date. For example, the previous high for Baltimore was 101, a high set in 1999.

http://www.signonsandiego.com/news/2010/jul/06/grsq-dreary-clouds-last-until-mid-week/

British Petroleums Big Derivative Problem

Posted By on July 6, 2010

WHAT WE KNOW ABOUT BP DERIVATIVES:

CSO (Credit Synthetic Obligations)

A study by Moody’s outlines that a BP bankruptcy would impair 117 Collateralized Synthetic Obligations (CSOs), which would lead to pervasive losses by a broad range of holders. The 117 effected is a startling 18% of the total CSOs outstanding, which is an indication of the scope and impact of BP financing globally. For those that remember the 2008 financial debacle, you will recall its epicenter was the collapse of Collateralized Debt Obligations (CDO)  associated with mortgages and Credit Default Swaps (CDS) of financial companies impacted. CSOs are even more leveraged and toxic.

The exhibit above lists CSOs (excluding CSOs backed by CSOs) with over 3% exposureto the five companies involved in the Gulf of Mexico incident.

To quote Moody’s:

In the event of BP’s restructuring or bankruptcy, CSO transactions referencing BP or its affected subsidiaries may experience what is called a “credit event.” If the credit event occurs, the CSO transactions will have to meet their payment obligations to the protection buyers, which will result in the loss of subordination to the rated CSO tranches. In cases where the subordination is no longer available, CSO investors will incur the loss.

We reviewed our entire universe of outstanding CSOs and determined that exposure to BP and its rated subsidiaries appears in 117 (excluding CSOs backed by CSOs) transactions, which represents approximately 18% of global Moody’s-rated CSOs. Exposure ranged from 0.26% to 2% of the respective reference portfolios. The transaction with the largest exposure to BP and its subsidiaries is Arosa Funding Limited – Series 2005-5.

Restructuring or Bankruptcy of Other Oil Companies Involved in the Spill Also Affects CSOs. In addition, we assessed Moody’s-rated CSO exposure to the other four companies and their subsidiaries that were involved in the Gulf of Mexico incident, which are Halliburton, Anadarko Petroleum, Transocean Inc., and Cameron International. Halliburton appears in 43 CSOs, Anadarko Petroleum appears in 28 CSOs, Transocean Inc. appears in 79 CSOs, and Cameron International appears in 6 CSOs. We recently changed the credit outlooks for Transocean and Anadarko Petroleum, as well as their rated subsidiaries, to negative from stable because of uncertainties related to the companies’ involvement in the Gulf of Mexico incident and potential financial liabilities associated with it. The CSOs referencing one or more of these issuers would face credit event consequences in a scenario where any of them restructures or enters bankruptcy.

We need to recall that Transocean was the owner /operator of Deepwater Horizon with 131 of the actual 137 employed by Transocean (RIG) and that Anadarko (APC) was BP’s 25% partnership holder in the well. Cameron International (CAM) was the builder of the faulty blowout preventer and Halliburton (HAL) the contractor for the well cementing operation in sealing the 13,350 foot Macondo drill site. These players will no doubt be heavily involved in the litigation and compensation settlements, but additionally will have collateral damage on other oil industry participants as they are forced to raise cash for litigation and claims.

 http://home.comcast.net/~lcmgroupe/2010/Article-Sultans_of_Swap-British_Petroleum.htm

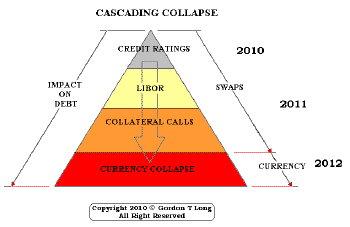
The Reverse Pyramid

Posted By on July 6, 2010

Reverse Pyramid

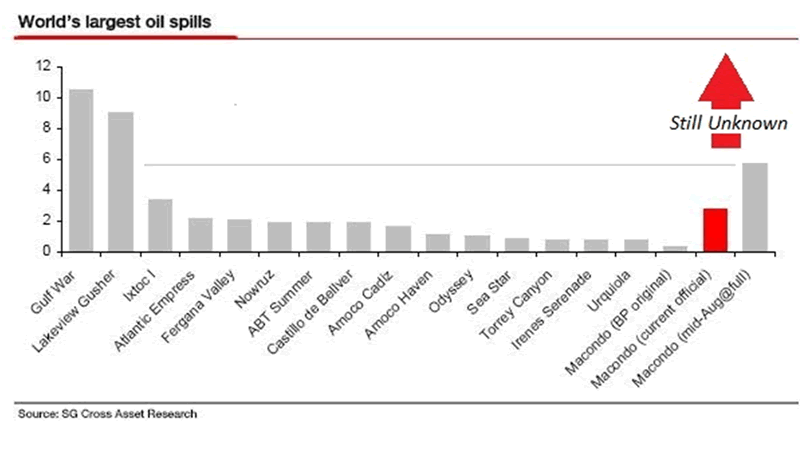
The Worlds Largest Oil Spills

Posted By on July 6, 2010

 Worlds Largest Oil Sills

What’s Hot…..Can You Say New York?

Posted By on July 6, 2010

By Christopher Martin        July 6, 2010

    The New York Independent System Operator, which controls the state’s power grid and market, ordered cuts to customers that participate in demand reduction programs as hot weather drove consumption near the record high.

Power demand rose to 33,450 megawatts as of 4:22 p.m., even after the grid operator asked some commercial customers in the city, representing about 400 megawatts, to reduce usage until 7 p.m., said Ken Klapp, a spokesman.

Without those cuts from “interruptible customers” that get a discount on electricity bills for participating, use today may have surpassed the 33,939-megawatt record reached on Aug. 2, 2006. Demand on Long Island hit an all-time high.

More than 4,000 customers in the five New York boroughs had lost electricity service as the hot weather strained grids, Con Ed said on its website. The utility expected to restore most of them by 7 p.m.

Wholesale electricity in the city reached $185.94 a megawatt-hour as demand surged, and on Long island climbed to $250, according to the grid operator. The average price for utilities such as Con Ed was $100.85 at 4 p.m. local time.

Power demand on Long Island reached a record 5,815 megawatts as of 4:30 p.m., topping the previous high of 5,792 on Aug. 3, 2006.

More at: http://www.bloomberg.com/news/2010-07-06/new-york-city-may-get-record-power-demand-as-temperature-set-to-break-100.html

A Whale Awaits EPA and Jones Waiver In The Gulf Of Mexico

Posted By on July 5, 2010

A Whale Awaits EPA and Jones Waiver   The world’s largest oil skimmer vessel arrived in the Gulf and has docked in Louisiana since June 30 awaiting U.S. official review and approval. According to the Associated Press (video below), the massive vessel?called “A Whale”– is 3 1/2 football fields long and 10-story high. It’s outfitted with 12 vents on either side of its bow.  Once deployed, the ship could vacuum about 21 million gallons of oil fouled water per day. The oil would then be moved to another tanker for disposal, and the water would be pumped back into the Gulf.

Watch the video on You Tube:  http://www.youtube.com/watch?v=yV1Q5gEraJ0&feature=player_embedded#!

 
07/05/2010

By Dian L. Chu, Economic Forecasts & Opinions

The world’s largest oil skimmer vessel arrived in the Gulf and has docked in Louisiana since June 30 awaiting U.S. official review and approval.

The Taiwanese-flagged vessel was originally commissioned as a conventional oil tanker earlier this year in South Korea. But the ship’s owner, Taiwan shipping giant ?TMT (Today Makes Tomorrow) Shipping Offshore modified it into an oil skimmer immediately after the BP Deepwater Horizon rig explosion.

A Whale’s Big Gamble

TMT is making a pretty big gamble as the giant A Whalle has not gotten a contract from BP or the U.S. government.

According to the Associated Press (video below), the massive vessel called “A Whale”– is 3 1/2 football fields long and 10-story high. It’s outfitted with 12 vents on either side of its bow.

Once deployed, the ship could vacuum about 21 million gallons of oil fouled water per day. The oil would then be moved to another tanker for disposal, and the water would be pumped back into the Gulf.

Awaiting EPA & Jones Waiver

That technology; however, has never been used or even tested, and requires the sign-off from the U.S. Environmental Protection Agency (EPA).

Furthermore, the vessel could have another hurdle. It may need a waiver of the Jones Act from the Administration, as reported by a news clip from ABC 13 News.  The Jones Act of the United States prohibits foreign-flagged vessel and non-U.S. crew working in the U.S. Gulf.  Many said the Jones Act has hindered oil cleanup assistance offered by the foreign governments and entities. 

As of this writing, the behemoth A Whale is not yet ready to attack the Gulf of Mexico oil spill after a weekend of testing proved inconclusive, mostly due to the rough sea state caused by Hurricane Alex, according to Nola, quoting a statement from TMT on Monday, July 5, 2010.

Testing is said to resume as soon as the water is calmer. But the National Weather Service indicated that the current spate of bad weather is likely to last for the next few days

Locals Remain Frustrated

Meanwhile, many local officials were anxious to get most of the smaller oil skimmers, halted last week by Alex, back on track and were frustrated that the ?A Whale? can?t start working on the cleanup immediately.

And understandably, Louisiana Gov. Bobby Jindal said it was exasperating to have ?A Whale? anchored offshore instead of being put to immediate use.

BP Relief Wells On Track

So, it seems A Whale may need a while to finally skim at the U.S. Gulf.  But fortunately, weather has not affected the two relief wells by BP meant to finally plug the oil gusher. BP said early to mid-August is still the timeframe for the completion of the drilling.


Baltic Dry Freight Index Down 26th Day In Succession

Posted By on July 5, 2010

Baltic Dry Freight Index down nearly 3% today and for the 26th week in successuion!

By Definition:

The Baltic Dry Index (BDI) is a number issued daily by the London-based Baltic Exchange. Not restricted to Baltic Sea countries, the Index tracks worldwide international shipping prices of various dry bulk cargoes.   The index provides “an assessment of the price of moving the major raw materials by sea. Taking in 26 shipping routes measured on a timecharter and voyage basis, the index covers Handymax, Panamax, and Capesize dry bulk carriers carrying a range of commodities including coal, iron ore and grain.”[1]


Just Out From British Petroleum

Posted By on July 5, 2010

The oil spill in the Gulf of Mexico has so far cost BP $3.12 billion.  This, according to British Petroleum,  is the total amount to contain the spill and clean it up.  But…..  does not include business claims.

Illinois Stops Paying Its Bills, But Can’t Stop Digging Hole

Posted By on July 5, 2010

California and Illinois, and more than 40 others states, are broke!

By MICHAEL POWELL
Posted  July 5, 2010

CHICAGO — Even by the standards of this deficit-ridden state, Illinois’s comptroller, Daniel W. Hynes, faces an ugly balance sheet. Precisely how ugly becomes clear when he beckons you into his office to examine his daily briefing memo.

He picks the papers off his desk and points to a figure in red: $5.01 billion.

“This is what the state owes right now to schools, rehabilitation centers, child care, the state university — and it’s getting worse every single day,” he says in his downtown office.

Mr. Hynes shakes his head. “This is not some esoteric budget issue; we are not paying bills for absolutely essential services,” he says. “That is obscene.”

For the last few years, California stood more or less unchallenged as a symbol of the fiscal collapse of states during the recession. Now Illinois has shouldered to the fore, as its dysfunctional political class refuses to pay the state’s bills and refuses to take the painful steps — cuts and tax increases — to close a deficit of at least $12 billion, equal to nearly half the state’s budget.

More…

Is This Really Starting To Feel Like 1932 All Over Again?

Posted By on July 5, 2010

The U.S. workforce shrank by 652,000 in June, one of the sharpest contractions ever. The rate of hourly earnings fell 0.1pc. Wages are flirting with deflation.  So, can things get much worse?  Yes!

By Ambrose Evans-Pritchard
Published: 9:33PM BST 04 Jul 2010

Ambrose Evans-Pritchard: Comment


“Home sales are down. Retail sales are down. Factory orders in May suffered their biggest tumble since March of last year. So what are we doing about it? Less than nothing,” he said.

California is tightening faster than Greece. State workers have seen a 14pc fall in earnings this year due to forced furloughs. Governor Arnold Schwarzenegger is cutting pay for 200,000 state workers to the minimum wage of $7.25 an hour to cover his $19bn (£15bn) deficit.

Can Illinois be far behind? The state has a deficit of $12bn and is $5bn in arrears to schools, nursing homes, child care centres, and prisons. “It is getting worse every single day,” said state comptroller Daniel Hynes. “We are not paying bills for absolutely essential services. That is obscene.”

Roughly a million Americans have dropped out of the jobs market altogether over the past two months. That is the only reason why the headline unemployment rate is not exploding to a post-war high.

Let us be honest. The US is still trapped in depression a full 18 months into zero interest rates, quantitative easing (QE), and fiscal stimulus that has pushed the budget deficit above 10pc of GDP.

The share of the US working-age population with jobs in June actually fell from 58.7pc to 58.5pc. This is the real stress indicator. The ratio was 63pc three years ago. Eight million jobs have been lost.

The average time needed to find a job has risen to a record 35.2 weeks. Nothing like this has been seen before in the post-war era. Jeff Weninger, of Harris Private Bank, said this compares with a peak of 21.2 weeks in the Volcker recession of the early 1980s.

“Legions of individuals have been left with stale skills, and little prospect of finding meaningful work, and benefits that are being exhausted. By our math the crop of people who are unemployed but not receiving a check amounts to 9.2m.”

Republicans on Capitol Hill are filibustering a bill to extend the dole for up to 1.2m jobless facing an imminent cut-off. Dean Heller from Vermont called them “hobos”. This really is starting to feel like 1932.

Washington’s fiscal stimulus is draining away. It peaked in the first quarter, yet even then the economy eked out a growth rate of just 2.7pc. This compares with 5.1pc, 9.3pc, 8.1pc and 8.5pc in the four quarters coming off recession in the early 1980s.

The housing market is already crumbling as government props are pulled away. The expiry of homebuyers’ tax credit led to a 30pc fall in the number of buyers signing contracts in May. “It is cataclysmic,” said David Bloom from HSBC.

Federal tax rises are automatically baked into the pie. The Congressional Budget Office said fiscal policy will swing from
a net +2pc of GDP to -2pc by late 2011. The states and counties may have to cut as much as $180bn.

It is obvious what that policy should be for Europe, America, and Japan. If budgets are to shrink in an orderly fashion over several years – as they must, to avoid sovereign debt spirals – then central banks will have to cushion the blow keeping monetary policy ultra-loose for as long it takes.

The Fed is already eyeing the printing press again. “It’s appropriate to think about what we would do under a deflationary scenario,” said Dennis Lockhart for the Atlanta Fed. His colleague Kevin Warsh said the pros and cons of purchasing more bonds should be subject to “strict scrutiny”, a comment I took as confirmation that the Fed Board is arguing internally about QE2.

For more: http://www.telegraph.co.uk/finance/comment/ambroseevans_pritchard/7871421/With-the-US-trapped-in-depression-this-really-is-starting-to-feel-like-1932.html

OIL Slickonomics – Part 9 From Cumberland Associates

Posted By on July 4, 2010

President Obama looks like, well, you get the picture!  And you can stick a fork in BP, its done. ………..Here are some interesting comments from Cumberland.     The Sarasota fishmonger on Lemon St. now gets his shrimp from Sanibel.  Louisiana is dead for years, he said.  It will not come back in my lifetime.   $20 billion is too low and will prove to be insufficient to settle all legitimate claims.  This fund was created out of a political decision-making process. It was not derived directly through our multi-century evolved process of adjudicating disputes.  To be paid from the fund a claimant has to give up some rights.  He must settle early and when the ultimate damage claim is unknown as to final size. We will soon learn more about BP and Credit Synthetic Obligations (CSO) (derivitives).  One detailed analysis from Moody’s identifies 117 of them that may be impaired by BP credit downgrades. Remember, BP was once an AAA credit.  It is now BBB according to Fitch.
 
 
OIL Slickonomics – Part 9
July 4, 2010
Americans were troubled by a different British threat two hundred and thirty-four years ago when Jefferson’s famous declaration launched our grand experiment in democracy.  Now, as then, we Americans find ourselves immersed in debate and facing uncertainty. 
 
Then we fought a revolutionary war and rejected dominance from afar.  Now we have already lost a global energy war. We have not restrained our oil hunger.  We are presently dependent on foreigners for about ¾ of our oil needs.  The BP spill, its aftermath, and the Obama drilling moratorium now threaten to raise that percentage to a new all-time high level of 85% dependency.
In Jefferson’s time, the authentic tea party affirmed that taxation without representation was anathema.  America’s early decades codified some of our inalienable rights like free press, property ownership, and the right to a jury trial with a presumption of innocence.  Now our free press shows us daily photos of the oil flow, video of empty Pensacola beaches, the angst of a Louisiana Parrish president, and the business failure of the a Gulf shrimper.
 
Property was ill-defined at our origins because Jefferson could not achieve a united thirteen colonies any other way.  It took a century and a civil war to remove human beings from the definition of owned assets.  Our evolving system replaced dueling pistols with lawyers and debtors’ prisons with bankruptcy. 
 
Now lawyers duel in the GOM with hundreds and hundreds of actions.  Bankruptcy risk is rising, according to market-based pricing of BP and its partners.  An unprecedented $20 billion fund will bypass courts.  This settlement between BP and the US government breaks new ground in America.  In time, we shall see if the unintended consequences end up outweighing the value. 
 
Many analysts, including ourselves, believe $20 billion is too low and will prove to be insufficient to settle all legitimate claims.  This fund was created out of a political decision-making process. It was not derived directly through our multi-century evolved process of adjudicating disputes.  To be paid from the fund a claimant has to give up some rights.  He must settle early and when the ultimate damage claim is unknown as to final size. 
 
During the last two centuries our American government centralized.  Its powers grew.  After Jefferson, financial obligations evolved through three huge pre-World War II, multi-decade cycles of inflation and deflation, boom and bust. Crisis after crisis led to official attempts to prevent their repetition.  This effort has always been unsuccessful for Americans as our political system ebbs and flows between restrictive financial conservatism and liberalistic fiscal and monetary ingenuity. 
 
As the financial reform bill wends its way through Congress, the issue of BP’s global derivative exposure begins to surface in markets.  This is a global market measured in the trillions.  We will soon learn more about BP and Credit Synthetic Obligations (CSO).  One detailed analysis from Moody’s identifies 117 of them that may be impaired by BP credit downgrades. Remember, BP was once an AAA credit.  It is now BBB according to Fitch.
 
Friday’s employment report was unpleasant reading.  It affirmed our forecast of a very slow job recovery ahead in the US.  On July 4, 2010, the narrow, and headline-generating, computation shows that one of every ten Americans is looking for a job and unable to find one.  One of six is either underemployed or unemployed (we are using the U-6 or broad definition of unemployment).  Think about it: 17% of our willing and working-age citizens have income levels below their previous experience. 
 
In addition, our nation has watched trillions in housing wealth disappear.  Our homes, the most pervasively owned asset in America, have been the bastion of savings for our stabilizing middle class.  It is a damaged sector.  Its owners bear scars; its foreclosed former owners suffer.
 
The national statistics need one more month to be disaggregated in sufficient depth to estimate job losses from the BP spill and from the Obama moratorium.  Business condition reports compiled by the Atlanta and Dallas Fed regional banks will begin to discuss the economic pain in tourism, fisheries, and oil service industries.  We expect this to make for continued unpleasant reading.  If the Obama moratorium holds in its present form, we expect a million more job losses over the next few years to pile on the job losses to date. This is in addition to those originating in the loss of fisheries and tourism.  Obama may be destined to run for re-election in 2012 with a broadly computed (U-6) unemployment rate of 18-20%.  This November the Congress too will be faced with these numbers, which is why some incumbents have decided to retire.
 
In Sarasota, some locals seem relieved by NOAA’s latest probabilities of oil-slick landfall.  NOAA says the likelihood of the oil damage reaching the Florida Keys and Miami is greater than the chance of it hitting the Tampa-Naples stretch of Florida’s west coast.  Why?  NOAA says the shape of the continental shelf alters the direction of the currents.  We note, however, that the NOAA study looked only at models of the directional flows of GOM currents.  It did not consider hurricane activity. 
 
On July 4, one-third of America’s GOM is closed to fishing.  NOAA’s jurisdiction stops at the federal boundary.  Thus, Mexico, Cuba, or international treaty enforcement determines fishing prohibitions in the non-US Gulf.  
 
The Sarasota fishmonger on Lemon St. now gets his shrimp from Sanibel.  Louisiana is dead for years, he said.  It will not come back in my lifetime.
 
At Walt’s Seafood, at 4144 South Tamiami Trail, the manager told me his oysters now come from the Texas side of the GOM. I asked him about hurricane-induced changes and underwater dispersant plumes.  He offered me a blank stare.  I leave that up to the government to tell me what I can do, he said.
 
Walt’s had some July 4 special offerings to accompany a cold, crisp Sauvignon Blanc from Marlborough, New Zealand.  I thought about seafood, personal safety, trust in government, and the GOM.  I pondered the damage BP and its partners inflicted.  Moreover, I considered that this is now a five-state regional tragedy thanks to politics, which are making it worse. 
 
But what to eat?  Is it safe?  In the end, some flown in from New England Ipswich steamed clams and a Maine Lobster proved to be succulent. 
 
The belly is sated.  The wine was flavorful.  However, celebratory joy seems muted on this Fourth of July. 
 
David R. Kotok, Chairman and Chief Investment Officer
 
*********
Copyright 2010, Cumberland Advisors. All rights reserved.
The preceding was provided by Cumberland Advisors, Home Office: One Sarasota Tower, 2 N. Tamiami Trail, Suite 303, Sarasota, FL 34236; . This report has been derived from information considered reliable, but it cannot be guaranteed as to accuracy or completeness.
Cumberland Advisors supervises about $1.4 billion in separate account assets for individuals, institutions, retirement plans, government entities, and cash-management portfolios. Cumberland manages portfolios for clients in 43 states, the District of Columbia and in countries outside the U.S. Cumberland Advisors is an SEC registered investment adviser. For further information about Cumberland Advisors, please visit our website at www.cumber.com.
Please feel free to forward this Commentary (with proper attribution) to others who

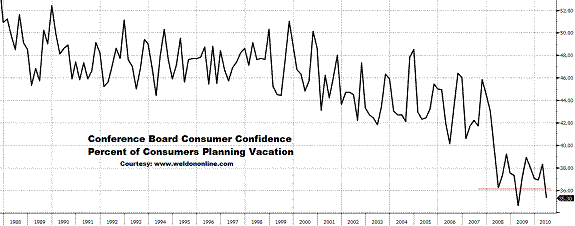
Consumers On Vacation….Or Not, As The Case May Be

Posted By on July 3, 2010

Interesting thoughts……..Data maven, Greg Weldon ( www.weldononline.com) shows that the number of people planning vacations in 2010 is down, dropping by over 35% in the last three years, and is now the second lowest number ever, only 2009 lower. Second lowest Ever.

Vacations

www.weldononline.com

Baltic Dry Shipping Index Approaching Just Above 1 Year Lows

Posted By on July 2, 2010

By Tyler Durden on 07/02/2010    Zero hedge

The decoupling theorists are about to experience a second smack down in 3 years. After the biggest bubble of 2008 blew up spectacularly and made beggars out of the Greek CEOs of various dry bulk shippers, only to see their fortunes go back to unchanged again, it looks like they may be retesting the benevolence of NetJets repo men for the second time. The BDIY chart has now completed a rather mutated head and shoulders, after dropping nearly two thousand points in the span of a month – the fastest plunge since the S&P 666 days. And with the Bank of China in liquidity salvage mode as reported earlier, look for much more gravity to come in this index.

Baltic Dry IndexMore at www.zerohedge.com

Gold Sentiment Negative……Hulbert Says Sets Up Contrarian Pattern

Posted By on July 2, 2010

Gold and gold stocks look absolutly terrible, so this makes a lot of sense!  The Hulbert Financial Digest has been tracking this kind of thing for over 30 years.


Friday July 2, 2010

ANNANDALE, Va. (MarketWatch) — Gold’s huge drop on Thursday is not the beginning of a new major leg down for the yellow metal.

That at least is the conclusion reached by a contrarian analysis of gold market sentiment. There does not currently exist the kind of stubborn optimism among gold timers that is the hallmark of major market tops.

Consider the average recommended gold market exposure among a subset of short-term gold market timers tracked by the Hulbert Financial Digest (as represented by the Hulbert Gold Newsletter Sentiment Index, or HGNSI). In the wake of Thursday’s 3.2% decline in gold bullion’s price, the HGNSI dropped 14.3 percentage points to 23.5%.

This not only is a big drop for just one day, which would, in and of itself, be a bullish omen, according to contrarian analysis. It’s also bullish that the HGNSI level that prevailed going into Thursday’s session was already surprisingly low, given how close gold bullion was to its all-time high reached earlier in June.

To put the current HGNSI level in context, consider that the HGNSI’s all-time high is 89.6%. So by no stretch of the imagination can current sentiment levels be described as excessively high.

This same conclusion is reinforced by comparing the HGNSI’s current level with where it stood six months ago. In early January, when gold bullion was trading for as low as $1,120 an ounce — more than $80 below the current price — the HGNSI stood at 60.9%. And early last December, furthermore, when gold bullion was trading for about $60 an ounce less than where it is today, this sentiment index got as high as 68%.

It’s most unusual for gold timers to become more bearish in the face of a rising market. But that, in essence, is exactly what they’ve done over the last six months. The far more typical pattern, of course, is for the HGNSI to rise as gold bullion rises, just as this sentiment index almost always tends to decline as the market falls.

That the gold timers didn’t adhere to this general pattern suggests that they are stubbornly clinging to a mood of skepticism, if not outright pessimism. And that’s bullish, according to contrarian analysis.

Bull markets, the saying goes, like to climb a wall of worry. And there definitely is a very strong such wall out there right now.

To be sure, since contrarian analysis was already reaching a bullish forecast prior to Thursday’s plunge, it’s worth stressing that sentiment is not the only factor that influences the market’s direction. And, I hope it goes without saying, no one indicator is always right.

But, over the three decades I’ve been tracking investment newsletters, the gold market has — on average — adhered to the contrarian pattern. That is, bullion has turned in far higher returns in the wake of low HGNSI levels than in the days and weeks following high readings.

The bottom line? The sentiment winds will be blowing strongly in the gold market’s sails in coming sessions.

Mark Hulbert is the founder of Hulbert Financial Digest in Annandale, Va. He has been tracking the advice of more than 160 financial newsletters since 1980.

Thoughts From Commodity Trader Jim Sinclair

Posted By on July 2, 2010

Thoughts For This Morning

Yesterday’s action in gold was started by a hedge fund that was experiencing a withdrawal of funds, as did most in the last quarter.

They attempted to take a profit and get money out of the market for redemptions by entering a sell for their gold in the cash and paper markets. This morning is margin call city in gold.

The .6 drop in those that have part time jobs in the Jobs Report means an additional 100,000 are out of work. That number was not added into the total.

www.jsmineset.com

Gross, Rosenberg Say Jobs Growth an Illusion

Posted By on July 2, 2010

It looks like the only ones in denial are the government officials, or is it that if they told us how bad things really are, everyone would freak?

Pacific Investment Management Co.’s Bill Gross and David Rosenberg, chief economist at Gluskin Sheff & Associates Inc., said June’s employment report indicates sluggish job growth and a slowing economy.

Employers cut 125,000 jobs last month, reflecting a drop in federal census workers, after an increase of 433,000 in May, Labor Department figures showed. Companies in the U.S. hired 83,000 workers, below the median forecast in a Bloomberg News survey for a gain of 110,000. The unemployment rate dropped to 9.5 percent from 9.7 percent as the labor force shrank.

“That’s a statistical illusion because you had this precipitous fall-off for the second month in a row in the labor force and without that, the unemployment rate would have gone up to 10 percent,” Toronto-based Rosenberg said during a radio interview on Bloomberg Surveillance with Tom Keene. “You can go as high as 16.5 percent, if you count the unemployed and under- employed.”

The pace of hiring signals it will take years for the world’s largest economy to recover the more than 8 million jobs lost during the recession that began in December 2007. The turmoil in financial markets brought on by the European debt crisis raises the risk that employment will slow, depriving American households of the income needed to maintain spending.

“The economy is slowing, not just in the United States, but globally,” Gross, co-chief investment officer at Pimco, said in a separate interview with Keene. “It’s a ‘new normal’ type of phenomenon. I don’t think the Federal Reserve can raise interest rates in the face of unemployment near 10 percent.”

Read the entire article at:http://www.bloomberg.com/news/2010-07-02/gross-rosenberg-say-employment-growth-reported-last-month-is-an-illusion.html

Inquiring Minds Want To Know…..Questions For The Federal Reserve

Posted By on July 1, 2010

Borrowing costs have tumbled in the past two months as concern that a debt crisis in Europe may spread boosted demand for the safety of bonds including mortgage-backed securities. The lower rates have failed to lift housing demand, which has tumbled since a tax credit for first- time and certain other buyers expired at the end of April.

The average price of $5.2 trillion of bonds guaranteed by government- supported Fannie Mae and Freddie Mac or federal agency Ginnie Mae climbed to 106.3 cents on the dollar yesterday, according to Bank of America Merrill Lynch’s Mortgage Master Index. That’s up from 104.2 cents on March 31, when the Federal Reserve ended its program purchasing $1.25 trillion of the debt.

MBS's Held by the Fed

But did the Fed really stop buying MBS?

The Fed planned to stop buying MBS at the end of this March, yet Fed MBS balances have increased by $45 billion since March 31. What will happen to the housing market when the Fed finally does begin to lower its MBS balances?

www.dailyreckoning.com

Pending Sales Of Existing U.S. Homes Decreased 30% In May

Posted By on July 1, 2010

Decline in sales of existing U.S. homes shows that the industry at the center of the financial crisis continues to  remain vulnerable in the absence of government support.  Sounds like everything  needs government support to exist today! 

By Shobhana Chandra              

July 1 (Bloomberg) — Manufacturing in the U.S. expanded in June at the slowest pace this year as factories received fewer orders and demand from abroad cooled. The Institute for Supply Management’s manufacturing gauge fell to 56.2 last month from 59.7 in May. Meanwhile, U.S. construction spending fell 0.2 percent in May and the index of pending home resales dropped 30 percent. Bloomberg’s Michael McKee and Margaret Brenna report. (Source: Bloomberg)

The number of contracts to purchase previously owned houses plunged in May by more than twice as much as forecast after a homebuyer tax credit expired.

The index of pending home resales dropped 30 percent from the prior month, figures from the National Association of Realtors showed today in Washington. The drop was the biggest in records dating to 2001 and compared with a 14 percent decrease forecast in a Bloomberg News survey of economists.

The decline shows that the industry at the center of the financial crisis remains vulnerable in the absence of government support. A stabilization in housing will depend on gains in incomes and employment that may stem foreclosures and give Americans the confidence to start buying again.

“Demand will be pretty depressed in the next few months,” Scott Brown, chief economist at Raymond James & Associates Inc. in St. Petersburg, Florida, said before the report.

The Institute for Supply Management’s manufacturing gauge fell to 56.2 last month from 59.7 in May. A reading greater than 50 points to expansion, and the median forecast of economists surveyed by Bloomberg News was 59. Initial jobless claims increased by 13,000 to 472,000 in the week ended June 26, Labor Department figures showed.

Forecasts for the decline in pending home sales ranged from 4 percent to 25 percent, according to a Bloomberg News survey of 36 economists. Sales rose 6 percent in April.

All four regions saw decreases in May, today’s report showed, led by a 33 percent plunge in the South. Sales also fell 32 percent in both the Midwest and Northeast and 21 percent in the West.

Compared with May 2009, nationwide pending sales were down 16 percent.

Pending home resales are considered a leading indicator because they track contract signings. Closings typically occur a month or two later, and are tallied in the Realtors’ existing- home sales report.

Sales of existing homes, which account for about 90 percent of the housing market, fell 2.2 percent in May from the prior month, the Realtors’ group said last week. New-house purchases, which make up the rest of the market and are tabulated when a contract is signed, plunged 33 percent to the lowest level on record in May, according to the Commerce Department.

http://www.bloomberg.com/news/2010-07-01/pending-sales-of-existing-u-s-homes-fell-30-in-may-on-tax-credit-s-end.html

Old Farmer’s Advice

Posted By on June 30, 2010

Old Farmer’s Advice:

Your fences need to be horse-high, pig-tight and bull-strong.  

Keep skunks and bankers at a distance. 

Life is simpler when you plow around the stump. 

A bumble bee is considerably faster than a John Deere tractor.

Words that soak into your ears are whispered…not yelled. 

Meanness don’t jes’ happen overnight. 

Forgive your enemies; it messes up their heads. 

Do not corner something that you know is meaner than you. 

It don’t take a very big person to carry a grudge. 

You cannot unsay a cruel word. 

Every path has a few puddles. 

When you wallow with pigs, expect to get dirty. 

The best sermons are lived, not preached.

Most of the stuff people worry about ain’t never gonna happen anyway. 

Don’t judge folks by their relatives. 

Remember that silence is sometimes the best answer. 

Live a good, honorable life.. Then when you get older and think back, you’ll enjoy it a second time. 

Don’t interfere with somethin’ that ain’t bothering you none. 

Timing has a lot to do with the outcome of a Rain dance. 

If you find yourself in a hole, the first thing to do is stop diggin’. 

Sometimes you get, and sometimes you get got. 

The biggest troublemaker you’ll probably ever have to deal with, watches you from the mirror every mornin’. 

Always drink upstream from the herd. 

Good judgment comes from experience, and a lotta that comes from bad judgment. 

Lettin’ the cat outta the bag is a whole lot easier than puttin’ it back in. 

If you get to thinkin’ you’re a person of some influence, try orderin’ somebody else’s dog around.. 

Live simply. Love generously. Care deeply. 
Speak kindly. Leave the rest to God. 

And,  watch out for that double trunk tree out back, ah it’s too late…….stuck!
 

Dog Stuck Between A Tree


Britain ‘Might Not Cope With Another Bank Emergency’

Posted By on June 30, 2010

So, the big question is….can the U.S. cope with another banking emergency?

By Sean O’Grady and James Moore
Tuesday, 29 June 2010

Britain’s mountain of debt could leave the country powerless to launch another rescue bid in the wake of a fresh financial crisis, the world’s central bankers warned yesterday. Their “club” – the Bank of International Settlements – presented in its annual report a frightening picture of the impact of a second banking emergency on heavily indebted nations such as Britain.

The Bank of England’s Governor, Mervyn King, has estimated that the Government has pumped as much as £1trillion of taxpayers’ money into the banking system. Billions of pounds were spent part-nationalising the Royal Bank of Scotland and Lloyds Banking Group, as well as fully nationalising Northern Rock, in an attempt to stave off collapse. Measures such as the “special liquidity” scheme propped up other lenders and prevented the system from freezing up.

But a BIS report warned yesterday that repeating these measures could be impossible. It said: “Events coming out of Greece highlight the possibility that highly indebted governments may not be able to act as a buyer of last resort to save banks in a crisis. That is, in late 2008 and early 2009, governments provided the backstop when banks began to fail. But if the debts of the government itself become unmarketable, any future bailout of the banking systemwould have to rely on external help.” Central bankers fear Europe is running out of “external backstops” that could step in, other than the US and the International Monetary Fund. This has unnerved capital markets in the EU, prompting some sharp swings in the value of shares and other financial instruments in recent days.

More…

National Debt Soars To Highest Level Since WWII

Posted By on June 30, 2010

U.S. debt has gone from 40% of the economy in 2008 to 62% of the economy by the end of 2010.  Yikes!

Jun 30, 2010

The federal debt will represent 62% of the nation’s economy by the end of this year, the highest percentage since just after World War II, according to a long-term budget outlook released today by the non-partisan Congressional Budget Office.

Republicans, who have been talking a lot about the debt in recent months, pounced on the report. “The driver of this debt is spending,” said New Hampshire Sen. Judd Gregg, the top Republican on the Senate Budget Committee. “Our existing debt will be worsened by the president’s new health care entitlement programs…as well as an explosion in existing health care and retirement entitlement spending as the Baby Boomers retire.”

At the end of 2008, the debt equaled about 40 % of the nation’s annual economic output, according to the CBO.

More at: http://content.usatoday.com/communities/onpolitics/post/2010/06/national-debt-soars-to-highest-level-since-wwii/1

Foreclosed On Homes Supply Grows, Record Amount To Come

Posted By on June 30, 2010

By Dan Levy    
 
Jun 30, 2010
 
Homes in the foreclosure process sold at an average 27 percent discount in the first quarter as almost a third of all U.S. transactions involved properties in some stage of mortgage distress, according to RealtyTrac Inc.

A total of 232,959 homes sold in the period had received a default or auction notice or were seized by banks, RealtyTrac said in a report today.“The discount will probably stay between 25 percent and 30 percent as lenders carefully manage the number of new foreclosure actions in order to avoid flooding the market,” Rick Sharga, RealtyTrac’s senior vice president for marketing, said in an interview.

“We’re clearly creating more properties that will be sold at distressed prices than the market is absorbing,” Sharga said. There were more than 250,000 new bank seizures in the first quarter.

The discount reflects the average sales price of homes in the foreclosure process compared with the average sales price of properties not in distress. About 31 percent of all U.S. sales in the quarter were of homes in some stage of foreclosure, RealtyTrac said.

Home foreclosures set a record for the second straight month in May, with increases in every state, as lenders stepped up property seizures, RealtyTrac said earlier this month. Bank repossessions climbed 44 percent from a year earlier and will probably set a record in the second quarter, the company said.

Distressed sales totaled more than 1.2 million last year, a 25 percent increase from 2008 and a more than four-fold rise from 2007, according to RealtyTrac.

Such transactions accounted for 29 percent of all sales last year, up from 23 percent in 2008 and 6 percent in 2007. The average foreclosure discount was 25 percent in 2009, 22 percent in 2008 and 26 percent in 2007.

A “normal” market would show foreclosures accounting for less than 2 percent of sales, Sharga said.

Bank-owned properties sold for an average 34 percent discount in the first quarter, up from 32 percent both in the previous quarter and a year earlier. Short Sales

“The competing forces will be bank-owned properties and short sales,” Sharga said. “The more short sales, the lower the average discount is likely to be.”

More at: http://www.bloomberg.com/news/2010-06-30/foreclosed-homes-in-u-s-sell-at-27-discount-as-distressed-supply-grows.html

The Free Lunch……Home Default Time It Takes To Evict

Posted By on June 29, 2010

Days Of Free Rent On Defaul Mortgage

“For the Baby Busters, It’s Downsize or Die”

Posted By on June 29, 2010

By: Richard Benson, SFGroup

Living realistically is not something anyone wants to do in an election year, and it may be especially difficult for the Baby Boomer generation to grasp, along with their children.  Over the last two decades as wages swelled, and job prospects were unlimited, the Baby Boomers became accustomed to living well beyond their means.   Moreover, if money wasn’t coming in fast enough, there was either a stock market or housing bubble to tap into to keep spending alive.  Even condominium buildings were built and given names with this in mind.

A high-rise condominium completed around 2005 in Boca Raton, Florida, was named “Luxuria”.  Models are lavishly decorated with names like “Milano” and “Toscana”.  The project back then was marketed as “a gem and one of the most spectacular preconstruction projects in Florida”.  One ad even claimed it would be “an exceptional privilege” to live there. 

The last time I drove by the “Models Open” signs were flapping in the wind, many units remained unsold, and prices were slashed (still extraordinarily expensive) with no buyers in sight.  My research also indicates that well over one-half of the units are still owned by the developer.   

American Boomers thought that the future would always bail them out, but the future is here and the house is upside down, the credit cards are maxed out, and job stability has vanished.  The prosperity they thought they had achieved was only a fantasy and the Boomers have now become the Baby Busters. 

When you actually sit down and examine the cost of living these days, the nickels and dimes can add up real fast.  After paying for food, phone, cable, electricity, newspapers, maintenance, gas, taxes, and insurance, most of us are left with only pennies.  Also, a healthy lifestyle – gym memberships, organic fresh fruits and vegetables – is beyond reach for many creating a frustrated society where diabetes is fast becoming a pediatric disease.  It’s no wonder fast food restaurants continue to thrive as they cater to the masses; they’re inexpensive for sure, but the food can make you obese and send you to the emergency room.

Surprisingly, the Boomers remain in denial and disbelief that the party is over, but perhaps not for long.  How can they vacation in Europe or buy that house in the Hamptons when their utility bills and property taxes are eating them alive, as they search for work?   Evidence suggests that the behavior of the Baby Busters may be evolving from being frozen like a deer in the headlights, to slow capitulation of letting go of the old lifestyle. Slowly, the second and third home that can’t be rented out is being sold or simply abandoned because it’s underwater.  The first home, a huge McMansion, is being swapped for a more affordable place one-third its size.  Not even the very rich can afford to heat or air-condition a place the size of a small hotel, and the Baby Busters are realizing they desperately need to be saving for retirement rather than spending into oblivion.   

As my wife and I watch these events unfold before our eyes, we both feel fortunate not to have fed into the frenzy.  We never really upsized, perhaps because of our upbringing, but our parents had common sense and a strong work ethic which fortunately rubbed off.   More likely, though, it’s because my wife and I both lived for decades in Manhattan where the cost of living is extraordinarily high.  An average two-bedroom 2-bath apartment there could cost a whopping $1.5 million or more, without a great view.  This price point is way beyond the cost of a modest apartment of the same size on the island of Palm Beach, yet we get free parking, a stunning view, and a swimming pool.  By focusing on keeping the monthly expense “nut” down and having the old-fashioned attitude that if you can’t buy it for cash, you shouldn’t buy it at all, we’ve discovered that, by luck, we managed to downsize by never really upsizing to begin with!

But time is not on our side.  Some Baby Busters only have a few years left to provide for retirement. Others might have as much as ten years, which can pass in the blink of an eye.  If a Boomer wants to avoid becoming a Buster (living on cheese wiz and saltines) they’ll need to do the following:  First, cut back by living within their means and stop incurring debt; Second, a safe retirement is unattainable when there is debt so you’ll need to cut back even more to pare down that debt; and, Third, you’ll need to save.  Saving is not easy in a zero interest rate environment but you’ll need to save even more because the Fed wants savers to get nothing!  Worse yet, counting on winning at the stock market casino is not a plan for the average saver, just a surefire way to make the owners of the casino (Goldman Sachs) rich. So, downsize, pay down debt, and tighten the belt again to save before it’s too late!

For far too many Baby Busters living frugally is like being held in purgatory, living without easy credit feels like an excruciatingly slow death, and saving money, while paying back debt, is a living hell.

For lack of a better word, my wife and I were “lucky” to have survived the turmoil of our generation.  As my wife politely reminds me from time to time, “it’s nice to live in heaven before you die”, but the joke is if we had upsized in the ‘90s like most Boomers, today we would be having a hell of a time.

http://news.goldseek.com/SFG/1277819902.php

RBS Tells Clients To Prepare For ‘Monster’ Money-Printing By The Federal Reserve

Posted By on June 28, 2010

This spells big big trouble for the world, it effects everyone every where……………..The ECRI leading indicator produced by the Economic Cycle Research Institute plummeted yet again last week to -6.9, pointing to contraction in the US by the end of the year. It is dropping faster that at any time in the post-War era.   Andrew Roberts, credit chief at RBS, is advising clients to read the Bernanke text very closely because the Fed is soon going to have to the pull the lever on “monster” quantitative easing (QE)”.   “We cannot stress enough how strongly we believe that a cliff-edge may be around the corner, for the global banking system (particularly in Europe) and for the global economy. Think the unthinkable,” he said in a note to investors. The Bank for International Settlements warns, sovereign debt crises are nearing “boiling point” in half the world economies.  There is no doubt that the Fed has the tools to stop this. “Sufficient injections of money will ultimately always reverse a deflation,” said Bernanke. The question is whether he can muster support for such action in the face of massive popular disgust, a Republican Fronde in Congress, and resistance from the liquidationsists at the Kansas, Philadelphia, and Richmond Feds. If he cannot, we are in grave trouble.


By Ambrose Evans-Pritchard,

International Business Editor

Published:  27 Jun 2010

Entitled Deflation: Making Sure It Doesn’t Happen Here”, it is a warfare manual for defeating economic slumps by use of extreme monetary stimulus once interest rates have dropped to zero, and implicitly once governments have spent themselves to near bankruptcy.

The speech is best known for its irreverent one-liner: “The US government has a technology, called a printing press, that allows it to produce as many US dollars as it wishes at essentially no cost.”

Bernanke began putting the script into action after the credit system seized up in 2008, purchasing $1.75 trillion of Treasuries, mortgage securities, and agency bonds to shore up the US credit system. He stopped far short of the $5 trillion balance sheet quietly pencilled in by the Fed Board as the upper limit for quantitative easing (QE).

Investors basking in Wall Street’s V-shaped rally had assumed that this bizarre episode was over. So did the Fed, which has been shutting liquidity spigots one by one. But the latest batch of data is disturbing.

The ECRI leading indicator produced by the Economic Cycle Research Institute plummeted yet again last week to -6.9, pointing to contraction in the US by the end of the year. It is dropping faster that at any time in the post-War era.

Full article at:http://www.telegraph.co.uk/finance/comment/ambroseevans_pritchard/7857595/RBS-tells-clients-to-prepare-for-monster-money-printing-by-the-Federal-Reserve.html


Newest Map…. Gulf Of Mexico Oil Slick

Posted By on June 28, 2010

Here is the latest Gulf oil map………..
 
Latest Gulf Oil Map

Copyright © 2026 The Stated Truth